Retail stores
Share the tenant mix, lease terms and occupancy. If your business uses the space, explain its operations and provide the financial information needed to support the review.
Explore commercial mortgagesTORONTO · MISSISSAUGA · THE GTA
A financing plan for your property.
Explore financing for retail stores, mixed-use properties and apartment buildings in Toronto, Mississauga and the GTA.
Tell us what you own, what you plan to buy or what you want to build.
Toronto officeServing borrowers across the GTA
Established in 1997Mortgage brokerage experience
Brokerage licence 10533Residential & commercial financing
RETAIL · MIXED-USE · APARTMENTS
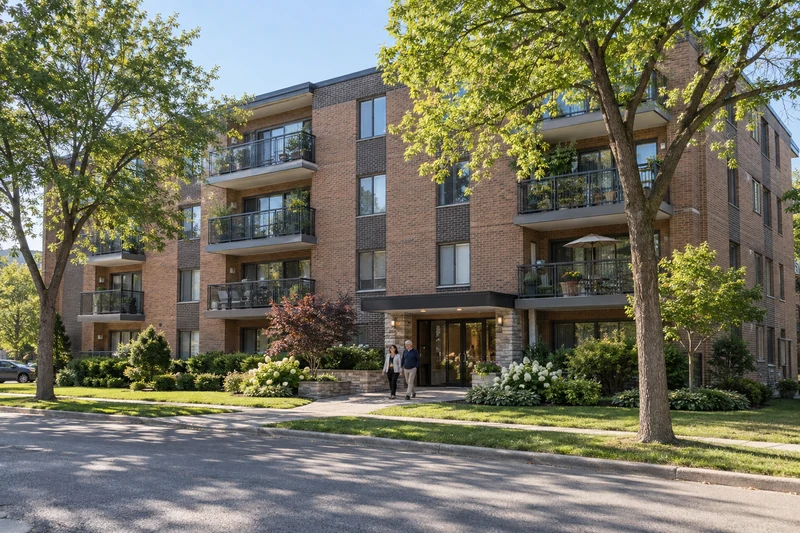
A retail storefront, a building with apartments above a shop and a purpose-built rental property each bring different questions to a mortgage review. The property’s use, leases, operating costs and condition help shape the discussion.
The Mortgage Providers helps GTA borrowers explore financing for stores and apartment buildings, including development projects. Tell us whether you are buying, refinancing, improving or building so we can discuss the information a lender may need.
A useful comparison connects the proposed borrowing with the property’s current performance and your ability to carry it through changes.
WHICH PROPERTY ARE YOU CONSIDERING?
Bring the details for each part of the building, including any space your own business occupies.
Share the tenant mix, lease terms and occupancy. If your business uses the space, explain its operations and provide the financial information needed to support the review.
Explore commercial mortgagesSeparate the retail and residential areas, rents and expenses. Explain entrances, access and the actual use of each space so the property can be presented clearly.
Explore first and second mortgagesBring the unit count, current rent roll, collection history and operating expenses. Include vacancies, planned repairs and the property-management arrangements.
Planning a new build? Explore construction financingA CLEARER PROPERTY REVIEW
A detailed property file helps distinguish current performance from what you hope to achieve after purchase or improvements.
Share the address, ownership structure, purchase price or mortgage balance, and the purpose and timing of the financing.
Gather leases, a current rent roll and income and expense records. Identify unpaid rent, vacancies and upcoming lease expiries.
Compare rates, payments, fees, term, security and any guarantees. Ask which appraisal, environmental or building-condition reports the lender requires before commissioning them.
Confirm the required equity, remaining conditions and closing costs. For a development, clarify staged funding, contingency funds and the longer-term repayment plan.
BEFORE YOUR CONVERSATION
Start with what is available. The team can explain what else is needed for the proposed financing review.
TEST THE PLAN AGAINST CHANGE
Consider what happens if a retail tenant leaves, a lease renewal takes longer or a building system needs replacement. Keep the assumptions visible when comparing financing options.
For refinancing, review the costs of replacing the existing mortgage and the funds left after fees and payouts. A larger loan is useful only if it fits the property plan and the borrower’s obligations.
If short-term private financing is proposed, ask how it will be repaid at maturity and what the alternative is if a sale or refinance takes longer than expected.
Explore private mortgage fundingTORONTO · MISSISSAUGA · GTA
A Toronto storefront with apartments above and a Mississauga rental building can have very different lease and expense profiles. Use the property’s records rather than a general neighbourhood assumption.
The Mortgage Providers welcomes enquiries across Toronto, Peel, York, Halton and Durham, including Brampton, Vaughan, Markham, Richmond Hill, Oakville and Burlington.
For a conversion or development, confirm the proposed use and municipal requirements with your project professionals before relying on the projected layout or income.
YOUR QUESTIONS
Answers about property types, documents and financing reviews.
Financing may be available depending on the property, borrower, income, equity and lender requirements. The Mortgage Providers welcomes enquiries about retail and apartment properties in Toronto, Mississauga and the GTA. Approval and terms require a review of the specific application.
Mixed-use properties can be considered, but lender criteria vary. Provide the retail and residential floor areas, unit details, leases and income for each part. The balance between commercial and residential use can affect the financing routes available.
A rent roll summarizes the rental units or spaces, their occupancy and rent details. For a financing review, include the current rent, lease dates, vacancies and any arrears or concessions. Keep it consistent with the leases and actual collection records.
There is no single percentage for every retail or apartment property. The lender considers the property type, value, income, borrower and financing structure. Ask what contribution is required and which fees, reserves or project costs must be funded separately.
No. CMHC’s standard rental housing insurance requires at least five rental units, alongside other property and borrower requirements. Mixed-use projects also face limits on their non-residential component. Ask whether an insured financing route can be considered for your project; eligibility and availability must be confirmed.
It may be possible if the lender approves the property, borrowing amount and proposed use of funds. Bring the current mortgage details, improvement budget and expected schedule. Compare the net funds after payouts and fees with the actual project cost.
Disclose them early and provide a realistic leasing plan. Separate existing income from projected rent and explain any incentives, work or time needed to attract tenants. Ask how the lender will assess vacancy and lease rollover in its review.
Yes, you can enquire about a proposed development. Share the land details, plans, budget, schedule and approval status. Construction financing may involve staged advances and additional conditions, with a separate plan for repayment or longer-term financing after completion.
LET’S REVIEW YOUR PROPERTY
Tell us about the property and your plans.
We’ll discuss what a financing review would need.
Sign up for our weekly or monthly newsletters packed full of the latest mortgage related news.