Sole proprietors and partners
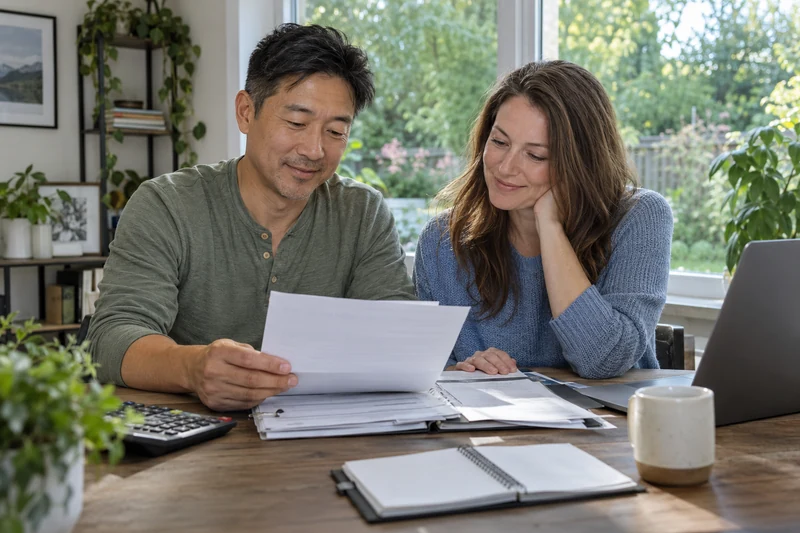
Bring your personal tax information and business records. Explain your ownership share, operating expenses and any changes in profit from one year to the next.
TORONTO · MISSISSAUGA · THE GTA
Your business. Your home. Your next step.
Mortgage options for business owners, contractors and freelancers in Toronto, Mississauga and across the GTA.
Tell us how you earn your income and what you are planning.
Toronto officeServing borrowers across the GTA
Established in 1997Mortgage brokerage experience
Brokerage licence 10533Residential & commercial financing
MORTGAGES FOR BUSINESS OWNERS
A self-employed mortgage is financing assessed using income from your business or independent work. Your documents may look different from a salaried employee’s, but the application still needs a clear picture of your ability to repay.
The Mortgage Providers helps self-employed borrowers in Toronto, Mississauga and across the GTA explore mortgage options. Start with how your business operates, how you receive income and whether you are buying, refinancing or approaching renewal.
Business sales, profit and personal income are different figures. Explain each clearly so the review reflects the money available to support your household and the proposed mortgage.
HOW DO YOU EARN YOUR INCOME?
Explain how you work and how money moves from the business to your household.
Bring your personal tax information and business records. Explain your ownership share, operating expenses and any changes in profit from one year to the next.
Explain how you pay yourself and distinguish your personal income from company revenue. Ask which corporate records and salary or dividend documents the review needs.
Describe your clients, contracts and payment cycle. Identify seasonal work, recent changes and any previous employment in the same field.
A CLEARER APPLICATION
Start the review early enough to gather documents and understand the conditions before relying on a financing amount.
Explain whether you are buying, refinancing or reviewing an upcoming renewal. Include the property details and your timing.
Set out your ownership, time in business, income sources and recent changes. Explain how the proposed payments fit alongside business commitments.
Ask which personal and business records are needed, what periods they should cover and how to provide them securely.
Review payments, rates, fees, flexibility and remaining conditions. If the timing is not right, discuss what information or preparation is missing.
BEFORE YOUR CONVERSATION
Depending on your circumstances, a review may require:
Ask which documents and periods apply to you before assembling the full package.
LOOK AT THE COMPLETE ARRANGEMENT
Allow for quieter months, taxes and business expenses when setting your household budget. A strong month of sales does not necessarily represent the income available every month.
If an alternative or private mortgage is proposed, ask why it fits, what the full costs are and how you will repay it. Being self-employed does not automatically mean you need private financing.
TORONTO · MISSISSAUGA · GTA
From a Toronto consultant to a Mississauga contractor or a business owner elsewhere in the GTA, the useful starting point is how you earn and document your income.
We welcome enquiries across Toronto, Peel, York, Halton and Durham, including Brampton, Vaughan, Markham, Richmond Hill, Oakville and Burlington.
Buying premises for your business? Explore our commercial mortgage page. Credit concerns? See our bruised credit mortgage page.
YOUR QUESTIONS
Answers about documents, business history and the review process.
Yes, self-employed borrowers can qualify for mortgages. The lender assesses the complete application, including income, credit, debts, down payment or equity and the property. The Mortgage Providers can review your circumstances and explore available options; approval is not guaranteed.
Not in every case. CMHC describes flexibility for some recently self-employed borrowers, while lender and product requirements vary. Explain your business start date, previous work experience and income history so the applicable requirements can be assessed.
Business revenue is not automatically qualifying personal income. Expenses, ownership and how you receive money from the business matter. Ask how the proposed lender calculates income and which records support that calculation.
Business expenses may reduce the income shown in your records. Whether a lender accepts any adjustments depends on its rules and supporting documents. Do not assume every expense can be added back. Discuss tax decisions with your accountant and mortgage documentation with the brokerage.
Explain both sources and provide the relevant personal and corporate records when requested. The lender decides what income it can accept. Company funds are not automatically available for personal mortgage qualification simply because you own the business.
Do not assume a self-employed product removes the need for verification. Documentation may differ across lenders, but the lender still sets its requirements. Ask what tax, business, banking or other evidence is needed before relying on a proposed financing amount.
Not necessarily. Self-employment alone does not determine the lender or rate. Available terms depend on the complete application. If a private mortgage is proposed, compare its costs, conditions and repayment plan with the other available routes.
It may be possible, subject to lender approval and sufficient qualifying income and equity. Share the current mortgage, purpose of the funds and business details. Include any payout charges and transaction fees when comparing the new arrangement.
LET’S DISCUSS YOUR NEXT STEP
Tell us how you work and what you are planning.
We’ll discuss what a mortgage review would need.
Sign up for our weekly or monthly newsletters packed full of the latest mortgage related news.